The AI Ecosystem at a Glance · 1/4
AI Circular Financing Map: Who Funds Whom
In Figure 1.2 of its October 2026 Global Financial Stability Report (GFSR), the International Monetary Fund (IMF) pointed out that deals of the form "take an equity investment, then commit to buying compute from the investor" are circulating among 14 AI companies. The IMF did not name the 14 companies, so this page matches the shape of the figure against publicly reported deals and presents an estimated circular map that assigns a company to each number.
- Investors (①–⑧): NVIDIA, Microsoft, Amazon, Alphabet (Google), SoftBank Group, AMD, Broadcom, Oracle
- Companies on both sides (⑨⑩): OpenAI (also an investor in Stargate, CoreWeave and Cerebras) and Stargate LLC (a joint venture)
- Investees (⑪–⑭): CoreWeave, Anthropic, Mistral AI (low confidence), SpaceX (formerly xAI)
The basic loop is "invest in an AI company → the AI company uses that money to buy the investor's GPUs or cloud." In 2026, guarantee- and SPV-based debt has been added on top, such as NVIDIA's lease guarantee for OpenAI's Ohio site (up to $105 billion) and the Broadcom residual-value-guaranteed SPV financing for Anthropic ($63 billion).
All mappings between numbers and companies are our own estimates. Neither the IMF nor the press has named the companies. Amounts are based on press reports and disclosures and include "up to" and conditional amounts ($ = US dollars).
Reading IMF Figure 1.2
Figure 1.2 is an arc diagram that lays out, from investors on the left to investees on the right, deals in which a company "receives equity or loans and in return commits future purchases (revenue) to the investor." According to press reports, it covers 14 deals announced since 2023.
| Element | Meaning | IMF total |
|---|---|---|
| Blue arcs (top, left → right) | Equity investment. Hyperscalers and chipmakers invest in financially weaker AI companies | ~$300bn |
| Green arcs (bottom, right → left) | Future revenue commitments. Money returns to investors as commitments to use cloud services or buy chips | ~$1.4tn |
| Red circles | Deal-linked debt. About $320bn sits with investees, including investor-guaranteed debt, contingent financing and off-balance-sheet debt | ~$650bn |
| Role of the numbers | ①–⑩ are investors and ⑨–⑭ are investees. ⑨ and ⑩ appear on both sides ("overlap" companies) | 14 deals |
Circular map (14 players)
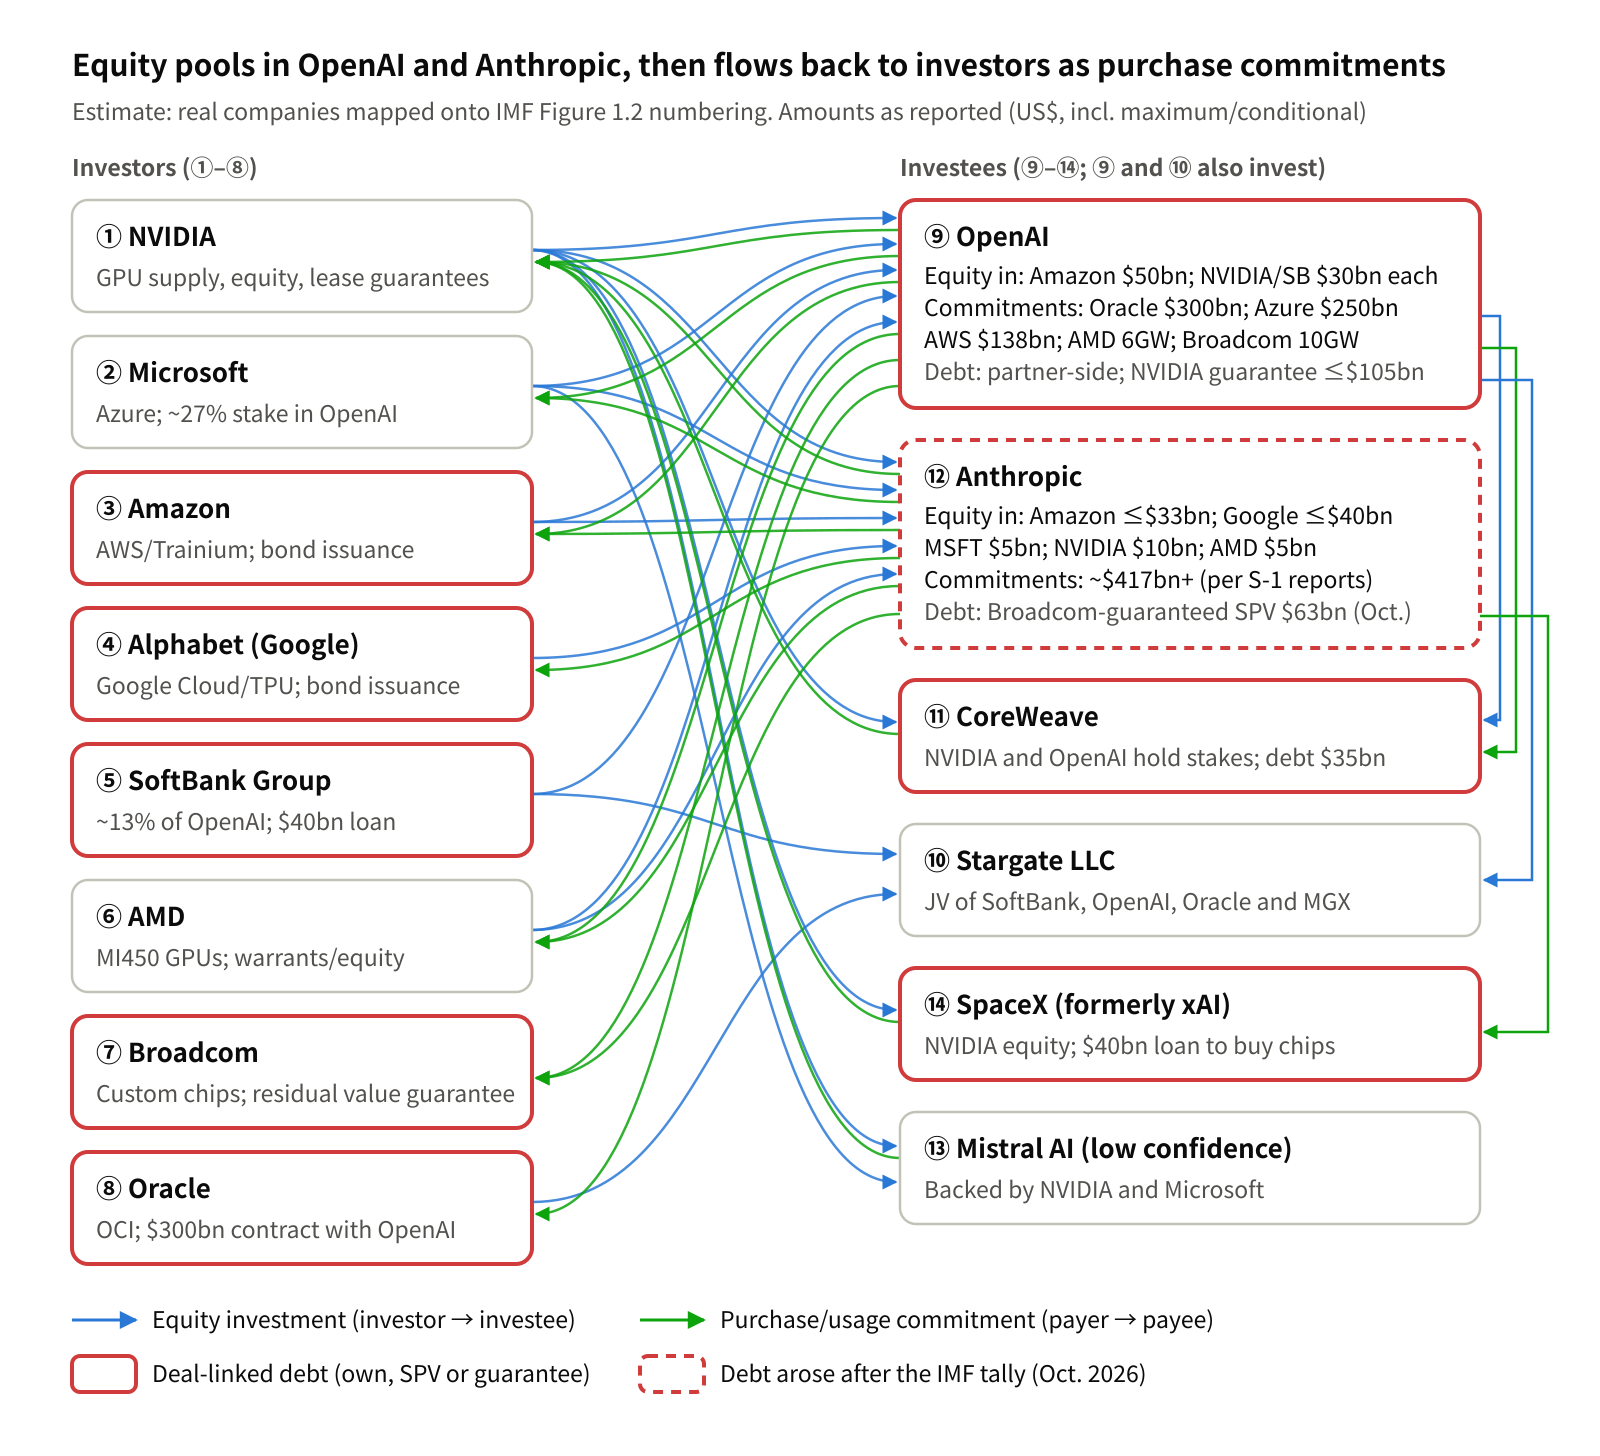
Most of the blue equity arrows from the eight companies on the left converge on OpenAI and Anthropic, and both companies' purchase commitments (green) flow back to the same eight. The lines on the far right show that OpenAI is also an investor in CoreWeave and Stargate, and that Anthropic is also a buyer of compute from SpaceX.
Estimated mapping table
For each number, we assigned the company whose deals best match the features in the figure. The order of the numbers (for example, whether ③ or ④ is Amazon) cannot be determined from the figure, so numbers with the same features should be read as interchangeable.
| No. | Estimated company | Features in the figure | Basis for the mapping (actual deals) | Confidence | Other candidates |
|---|---|---|---|---|---|
| ① | NVIDIA | Investor, no debt, most investees | $30bn in OpenAI, up to $10bn in Anthropic, an additional $2bn in CoreWeave, and an investment in xAI. Investees buy its GPUs | High | — |
| ② | Microsoft | Investor, no debt | Holds about 27% of OpenAI, with a $250bn Azure contract. Invested up to $5bn in Anthropic and won Azure usage | Medium | AMD |
| ③ | Amazon | Investor, with debt | Up to $50bn in OpenAI and up to $33bn cumulatively in Anthropic. Won AWS usage from both. Issues bonds to fund capex | Medium | Alphabet |
| ④ | Alphabet (Google) | Investor, with debt | Up to $40bn in Anthropic. Anthropic committed to about $200bn of Google Cloud over five years (reported) | Medium | Amazon |
| ⑤ | SoftBank Group | Investor, with debt | Cumulative investment in OpenAI of about $64.6bn (~13%), of which $30bn was funded with a $40bn bridge loan. Also invests in Stargate | Medium | Oracle (swap with ⑧) |
| ⑥ | AMD | Investor, no debt | Granted OpenAI warrants for about 10% of its shares and won 6GW of GPU purchases. Invested up to $5bn in Anthropic with a 2GW deal | Medium | Microsoft |
| ⑦ | Broadcom | Investor, with debt | Residual value guarantee on the chip-lease SPV for Anthropic ($63bn). Reported in the S-1 as a lender of up to $42bn. 10GW custom-chip deal with OpenAI | Low–Medium | Meta, MGX |
| ⑧ | Oracle | Investor, large debt | About $7bn invested in Stargate (reported). $300bn/5-year contract from OpenAI. $18bn of bonds and $38bn of related loans (Vantage sites), plus plans to raise another $45–50bn in 2026 | Medium | SoftBank (swap with ⑤) |
| ⑨ | OpenAI | Investor and investee, largest debt | Equity concentrates here, including a $122bn funding round. Little debt of its own, but about $100bn of partner-side debt (as of November 2025) and NVIDIA guarantees of up to $105bn are tied to it. Also an investor in Stargate and CoreWeave | Medium–High | — |
| ⑩ | Stargate LLC | Investor and investee, no debt | A joint venture funded by SoftBank, OpenAI, Oracle and MGX that invests in each site. Debt sits in site-level SPVs or with Oracle, not on the JV itself | Low | CoreWeave, MGX |
| ⑪ | CoreWeave | Investee, with debt | NVIDIA is a shareholder (added $2bn in January 2026) and CoreWeave buys its GPUs. OpenAI is also a shareholder with contracts of up to $22.4bn. Debt of about $35bn | Medium | Nebius, Nscale |
| ⑫ | Anthropic | Investee, no debt | Amazon, Google, Microsoft, NVIDIA and AMD invested, and Anthropic committed to using each company's cloud or chips. The Broadcom-related SPV debt dates from October 2026, apparently after the IMF's cut-off | Medium–High | — |
| ⑬ | Mistral AI | Small investee, no debt | Backed by NVIDIA and Microsoft; building its own cloud on NVIDIA chips | Low | Cerebras, Lambda |
| ⑭ | SpaceX (formerly xAI) | Investee, with debt | NVIDIA invested in xAI. After GPU-backed SPV financing, in October 2026 it was negotiating a $40bn loan to buy NVIDIA chips (FT report) | Low–Medium | Nscale, Crusoe |
Among ③④⑤⑦⑧, it is natural to read ⑧, which has the largest debt circle, as either Oracle or SoftBank. Oracle has little of the character of an equity investor, and whether the IMF counts it as an investor is one of the most uncertain points.
Four loop types and where the risk sits
The loops fall into four broad types. What they share is that part of the investors' revenue is supported by money the investors themselves put in.
- Chip loop (vendor financing): NVIDIA invests $30bn in OpenAI → OpenAI expands its infrastructure → the sites adopt NVIDIA chips. In Ohio, NVIDIA even guarantees the lease. AMD (GPU purchases in exchange for warrants) and Broadcom (chip leases in exchange for a residual value guarantee) follow the same pattern.
- Cloud loop: Amazon, Google and Microsoft invest in AI labs → the labs buy the investors' cloud under long-term contracts → cloud backlogs swell. Anthropic's Google contract is reported to account for more than 40% of Google's cloud backlog (about $2tn).
- Debt loop: SoftBank borrows $40bn from banks and invests it in OpenAI → OpenAI orders compute from Stargate and Oracle → Oracle builds with bonds and loans. The same future OpenAI revenue is the repayment source for several layers of debt.
- Neocloud loop: NVIDIA invests in CoreWeave and guarantees capacity → CoreWeave borrows to buy NVIDIA GPUs → and rents them to OpenAI, Meta and Anthropic. OpenAI is also a CoreWeave shareholder.
Risk concentrates in three places.
- Concentration in a few investees: The IMF notes that "a handful of investees hold most of the financing and revenue commitments." If OpenAI and Anthropic cannot earn enough, valuation losses on the equity, difficulty servicing debt and defaults on revenue commitments would happen at the same time (the report calls this "wrong-way risk").
- Gap between revenue and commitments: Anthropic's April–June 2026 revenue was $11.6bn (per S-1 reports), against future compute payments of more than about $400bn. OpenAI expects to spend $750bn on compute through 2030 (Siècle Digital/WSJ).
- Less visible debt: At Abilene, New Mexico, Ohio and in Anthropic's Broadcom lease, debt tends to sit outside the AI companies' balance sheets in SPVs or guarantees. The lenders range from Japanese banks (Mizuho, SMBC, MUFG) to large US banks and private credit funds (Apollo, Blackstone, Blue Owl).
Peripheral players beyond the 14
Outside the 14 companies, further layers of firms supply money and compute to the same loop. Think of it as a second ring drawn around the figure.
| Layer | Companies | Role in the loop |
|---|---|---|
| Neoclouds | Nebius, Nscale, Lambda, Crusoe, Fluidstack, Volta | Large contracts from Microsoft, Meta and Anthropic. Anthropic committed up to about $44.6bn to Nscale and about $41.3bn to Lambda. Many are backed by NVIDIA |
| Other hyperscalers | Meta | Major customer of CoreWeave (over $35bn in total), Nebius (up to $27bn), Oracle and Google Cloud. Its Hyperion site is off balance sheet through a $27bn JV with Blue Owl |
| Sovereign capital | MGX (UAE) | Invests in OpenAI's funding rounds and in Stargate |
| Data center development & power | SB Energy, Vantage, Crusoe, Related | Build and own sites and collect rent under long-term leases. NVIDIA invested $1.5bn in SB Energy |
| Private credit | Apollo, Blackstone, Blue Owl, Pimco, KKR, Brookfield | Subordinated and mezzanine tranches of SPVs, Abilene, the Anthropic chip lease and more. NVIDIA is reported to partner with them on customer financing |
| Banks | JPMorgan, Goldman Sachs, BofA, Citi, Morgan Stanley, Mizuho, SMBC, MUFG | SoftBank's bridge loan, Stargate site SPVs, Oracle-related loans and more. Japanese banks have large exposure |
| Component suppliers | TSMC, SK hynix, Samsung, Micron | Do not invest, but are the final recipients of chip demand inflated by the loop. SK hynix shares reportedly fell after the IMF report was published |
Note that SpaceX (formerly xAI) is both an investee and a lender of compute to Anthropic and Google. Anthropic has ordered up to $120.5bn of NVIDIA-based compute from SpaceX, and SpaceX is seeking to buy those chips with a $40bn loan. Loops are spreading even between competitors.
Extended circular map (from lenders to components)
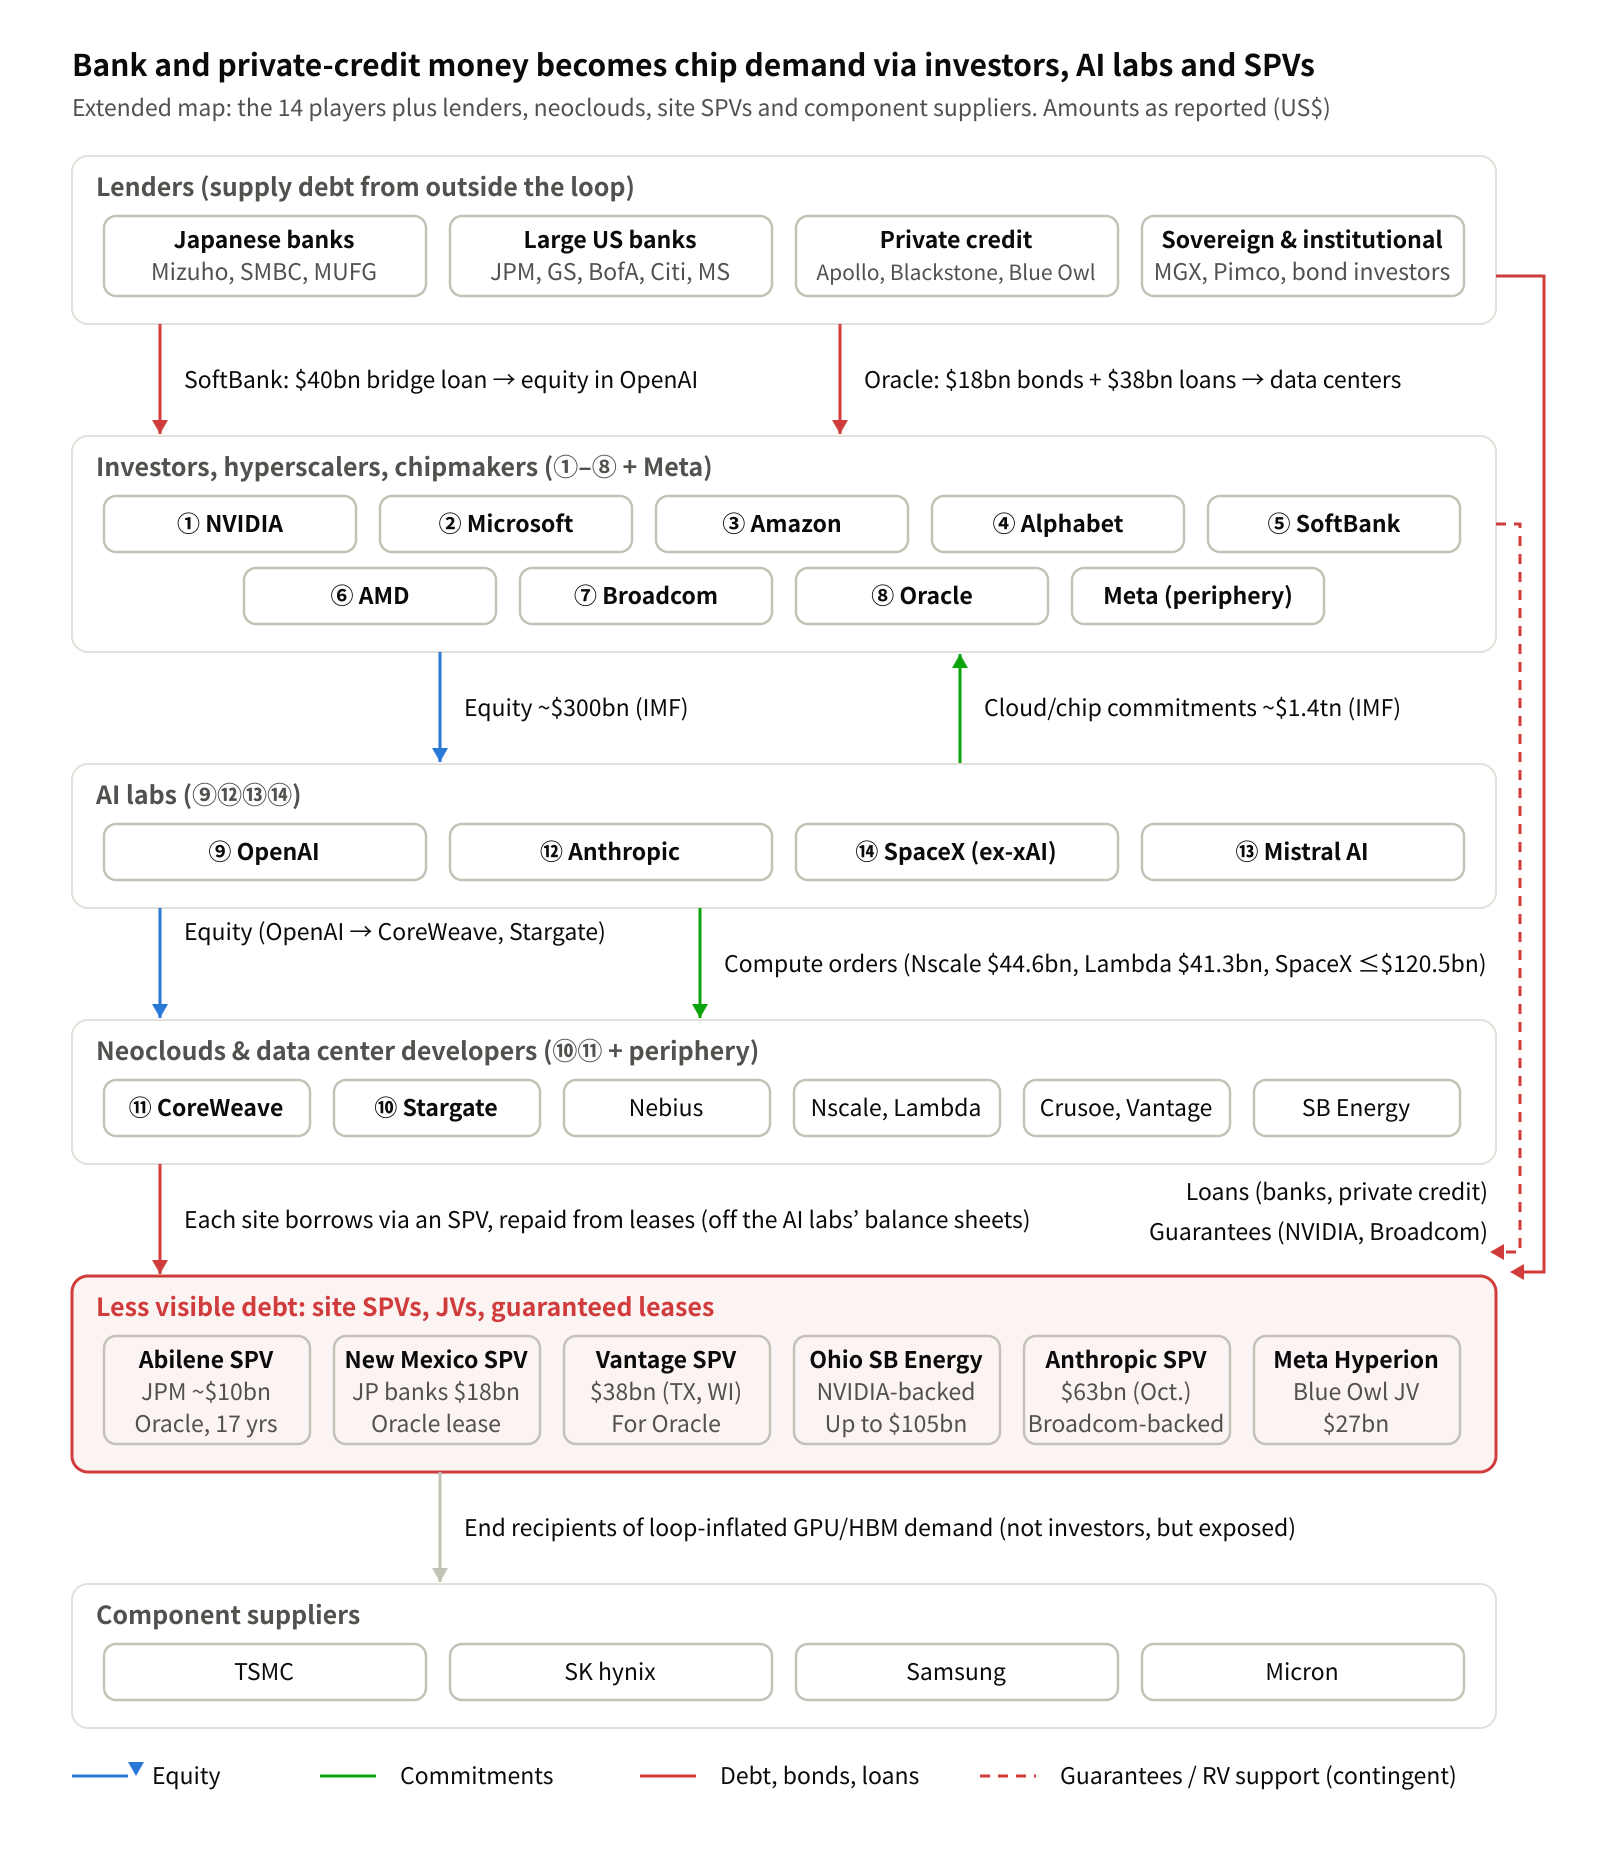
Reading from top to bottom, money from banks and private credit enters the investor layer (red borrowing) and the site SPVs (red line on the far right). Equity from the investor layer to the AI labs (blue) faces the purchase commitments flowing back from the labs to the investors (green). The labs' orders become the repayment source for neocloud and site-SPV borrowing, and guarantees from NVIDIA and Broadcom (dashed red) support those SPVs. The component suppliers at the bottom neither invest nor guarantee, but are the final recipients of the demand this loop inflates.
Key deals: the facts
Announced or reported deals, newest first. Amounts are as reported and include "up to" and conditional amounts.
| Date | Parties | Type | Details and amount | Source |
|---|---|---|---|---|
| Oct 2026 | Broadcom → Anthropic | Debt (guaranteed SPV) | BofA, Citi, Morgan Stanley and Blackstone lend $63bn. The SPV buys Broadcom chips and leases them to Anthropic. Broadcom provides a residual value guarantee | Khaleej Times/Reuters |
| Oct 2026 | Anthropic (S-1 filing) | Revenue commitment | Future compute payments of about $417bn (reports range from $450bn to $518bn). Google $114.5bn+, AWS $110bn+, Azure $44.9bn+, Broadcom lease about $161.2bn, SpaceX up to $120.5bn | Baxtel, PPC Land |
| Oct 2026 | SpaceX (formerly xAI) ← Apollo and others | Debt | Negotiating about $40bn of borrowing ($10bn bank loan + $30bn investment-grade bonds) to buy NVIDIA chips | investingLive/FT |
| Aug 2026 | NVIDIA → OpenAI (SB Energy) | Debt guarantee + equity | Guarantees up to $105bn of lease and power payments for the Ohio site (8 IT-GW). $1.5bn equity in SB Energy. NVIDIA is the exclusive chip supplier | Axios |
| Aug 2026 | CoreWeave | Debt | April–June revenue $2.58bn, backlog $104bn, debt $35bn | Runtime Wire |
| Jul 2026 | AMD → Anthropic | Equity + revenue commitment | Up to $5bn of equity (conditional). Anthropic deploys up to 2GW of MI450 | Forkast |
| May 2026 | Anthropic Series H | Equity | $65bn at a $965bn valuation | Tech Insider |
| Apr–May 2026 | Alphabet → Anthropic | Equity + revenue commitment | Up to $40bn of equity ($10bn upfront, $30bn conditional). Anthropic commits about $200bn to Google Cloud over five years and about 5GW of TPUs (reported) | BTW Media |
| Apr 2026 | Amazon → Anthropic | Equity + revenue commitment | New $5bn plus up to $20bn conditional (up to $33bn including the existing $8bn). Anthropic commits more than $100bn to AWS over 10 years, up to 5GW | Global Data Center Hub |
| Mar–Apr 2026 | OpenAI funding round | Equity | $122bn at an $852bn valuation. Amazon up to $50bn, NVIDIA $30bn, SoftBank $30bn | Yahoo Finance |
| Mar 2026 | SoftBank ← bank syndicate | Debt | $40bn bridge loan for an additional investment in OpenAI (JPMorgan, Goldman, Mizuho, SMBC, MUFG) | TNW |
| Feb 2026 | Amazon → OpenAI | Revenue commitment | AWS contract expanded by $100bn over eight years, about 2GW of Trainium | ComputePrices |
| Feb 2026 | NVIDIA → OpenAI | Equity | Dropped the September 2025 letter of intent for up to $100bn and switched to a $30bn equity investment | Outlook Business |
| Jan 2026 | NVIDIA → CoreWeave | Equity | $2bn at $87.20 per share. Supports building more than 5GW by 2030 | CoreWeave 8-K |
| Jan 2026 | OpenAI → Cerebras | Revenue commitment + warrants | More than $20bn, 750MW. OpenAI receives warrants for Cerebras shares | ComputePrices |
| Nov 2025 | Microsoft, NVIDIA → Anthropic | Equity + revenue commitment | Microsoft up to $5bn, NVIDIA up to $10bn. Anthropic commits $30bn to Azure (later revised to $44.9bn+) | PPC Land |
| Nov 2025 | OpenAI's partners | Debt | OpenAI-related debt at Oracle, SoftBank, CoreWeave, Blue Owl, Crusoe and others totals about $100bn. The Abilene SPV borrowed about $10bn from JPMorgan; the New Mexico SPV borrowed $18bn, mainly from Japanese banks | Irish Times/FT |
| Oct 2025 | Microsoft ↔ OpenAI | Equity + revenue commitment | After the restructuring Microsoft holds about 27%. OpenAI buys an additional $250bn of Azure | ComputePrices |
| Oct 2025 | AMD, Broadcom → OpenAI | Revenue commitment (+ warrants) | AMD supplies up to 6GW of GPUs and grants warrants to OpenAI; Broadcom supplies 10GW of custom chips | Wikipedia: Stargate |
| Sep 2025 | Oracle ← OpenAI | Revenue commitment + debt | OpenAI signs a $300bn, five-year, 4.5GW contract. Oracle issues $18bn of bonds and is later sued by bondholders | DCD |
| Jan 2025– | Stargate LLC | Equity | OpenAI and SoftBank about 40% each (about $19bn each); Oracle and MGX about $7bn each (reported) | Wikipedia: Stargate |
Facts vs estimates, caveats
- Confirmed (based on reports and disclosures): The amounts and dates in "Key deals: the facts," and the IMF totals (about $300bn of equity, about $650bn of debt of which about $320bn sits with investees, about $1.4tn of revenue commitments, 14 deals).
- Estimated: Every mapping between numbers and companies. Neither the IMF nor the press has named the companies, and we could not find a public version of the underlying source, Chen, Gautam, and Wu (2026).
- Timing gap: The IMF report was published in mid-October 2026, so it most likely excludes Anthropic's S-1 and the $63bn Broadcom-related financing from late October. This is consistent with ⑫ (Anthropic) having no debt circle.
- Ranges in the numbers: Reports put Anthropic's compute commitments at $417bn, $450bn or $518bn, and some amounts are blank in the public S-1. For Google there are two figures: "about $200bn over five years" (reported) and "at least $114.5bn" (S-1 summary).
- Mapping caveats: Oracle has little of the character of an equity investor, and confidence is also low for Stargate LLC and Mistral AI. Meta, MGX, Nebius or Nscale may be among the IMF's 14.
Sources
Sources for individual deals are listed in "Key deals: the facts." Other sources:
- IMF, Global Financial Stability Report, October 2026, Figure 1.2
- TNW: IMF warns $1.4tn in circular AI deals
- Servola: IMF finds $1.4 trillion of revenue commitments in 14 AI deals
- Metir AI: IMF GFSR Oct 2026 AI circular financing
- Alpesh Patel: The $1.4 Trillion Circle
- Sovereign Magazine: Anthropic IPO, $518bn compute commitments
- DCD: Oracle to raise up to $50bn in 2026
- ComputePrices: AI compute deals