Macro Risk Monitor: June 2026 Back Number (MR-2026-06)
This issue was prepared retrospectively. No monthly commentary was written at the time. This page was built later from figures prepared for the July 2026 issue. The reasons for scores therefore state only changes in numbers, with no interpretation of the news at the time.
There are no country SURI data for June; the aggregates are interpolated between January and July. FCO is shown under the current v2.1; it is 5.22 under v2.0.
Conclusions of this report
- GRCS5 is 80.27, above 80 for the first time. It rose 1.28 and entered the Severe band.
- Financial stress stays low. FCO is 4.32 (Low) and FFI is 69.90 (High). HY OAS is 2.75% and VIX 16.45.
- Oil fell and transits partly recovered. Brent fell from $107.5 to $85.4 and Hormuz transits rose from about 20 to about 35 per day.
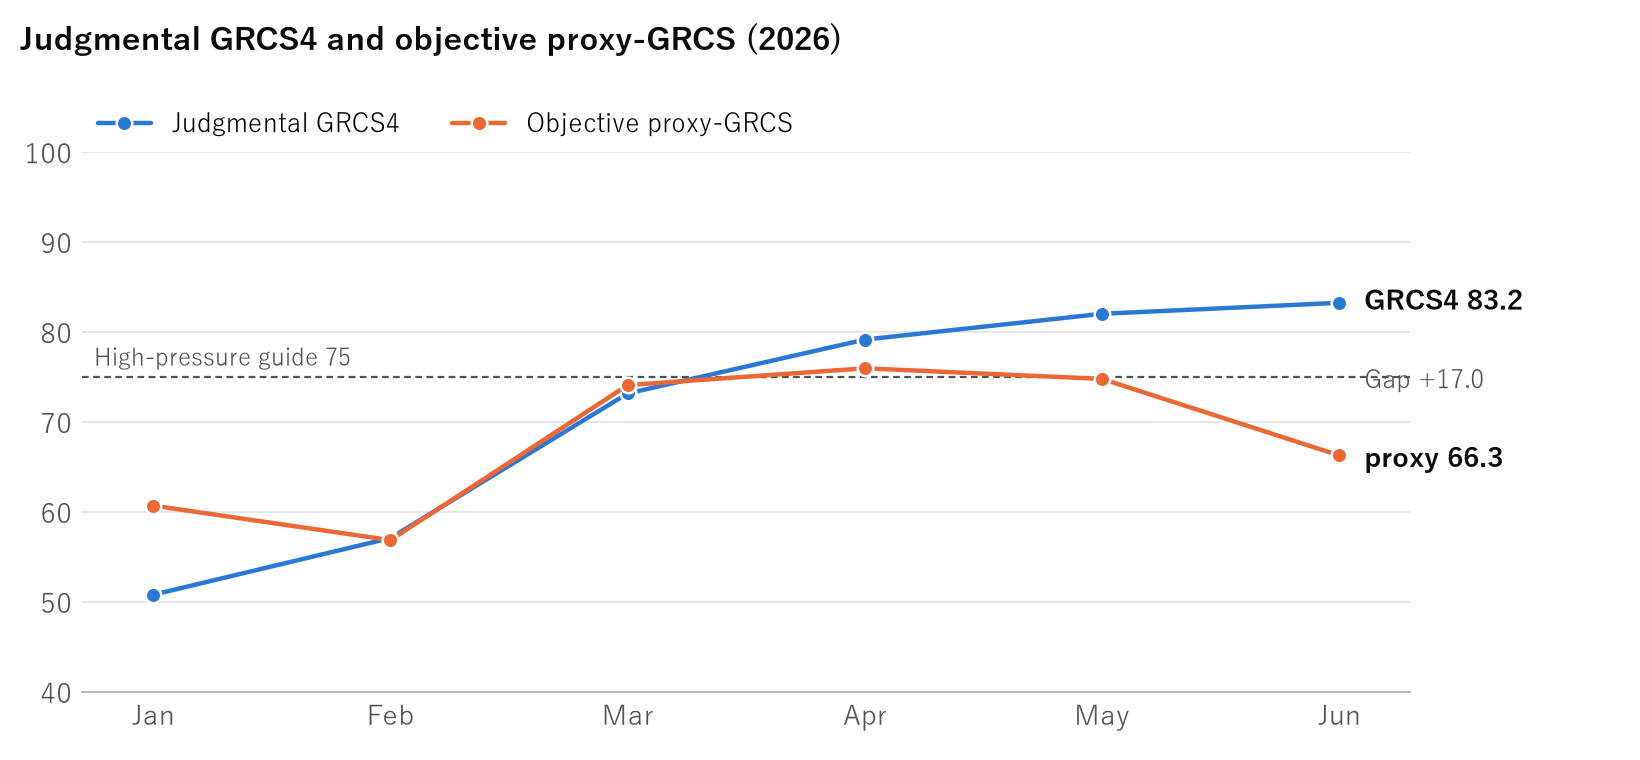
- The gap between judgmental and objective widened. Objective proxy-GRCS fell from 74.8 to 66.3 while judgmental GRCS4 rose, leaving a gap of +16.9. proxy-GRCS was calculated later.
- Countries with SURI ≥ 60 are 9, on interpolated values. RCEI is 76.55. The prediction log had not yet begun.
Contents
Where we stand
| Index | What it measures | This month | Prior month | Change | Band |
|---|---|---|---|---|---|
| GRCS5 | Compound macro pressure (five risks) | 80.27 | 78.99 | +1.28 | Severe |
| GRCS4 | For comparison across eras (excludes ⑤ AI) | 83.23 | 82.01 | +1.22 | Severe |
| FFI | Financial fragility (weakness built up in calm times) | 69.90 | 69.50 | +0.40 | High |
| FCO | Financial stress (tension occurring now) | 4.32 | 3.58 | +0.74 | Low |
| SCI | Strength of the chains | 74.00 | 70.80 | +3.20 | — |
| SURI≥60 | Countries with social unrest risk of 60 or more (of 20) | 9 | 8 | +1 | — |
| RCEI | Regional conflict escalation | 76.55 | 76.15 | +0.40 | Severe |
Bands are thresholds set for each index. See The Risk Measurement Model for definitions.
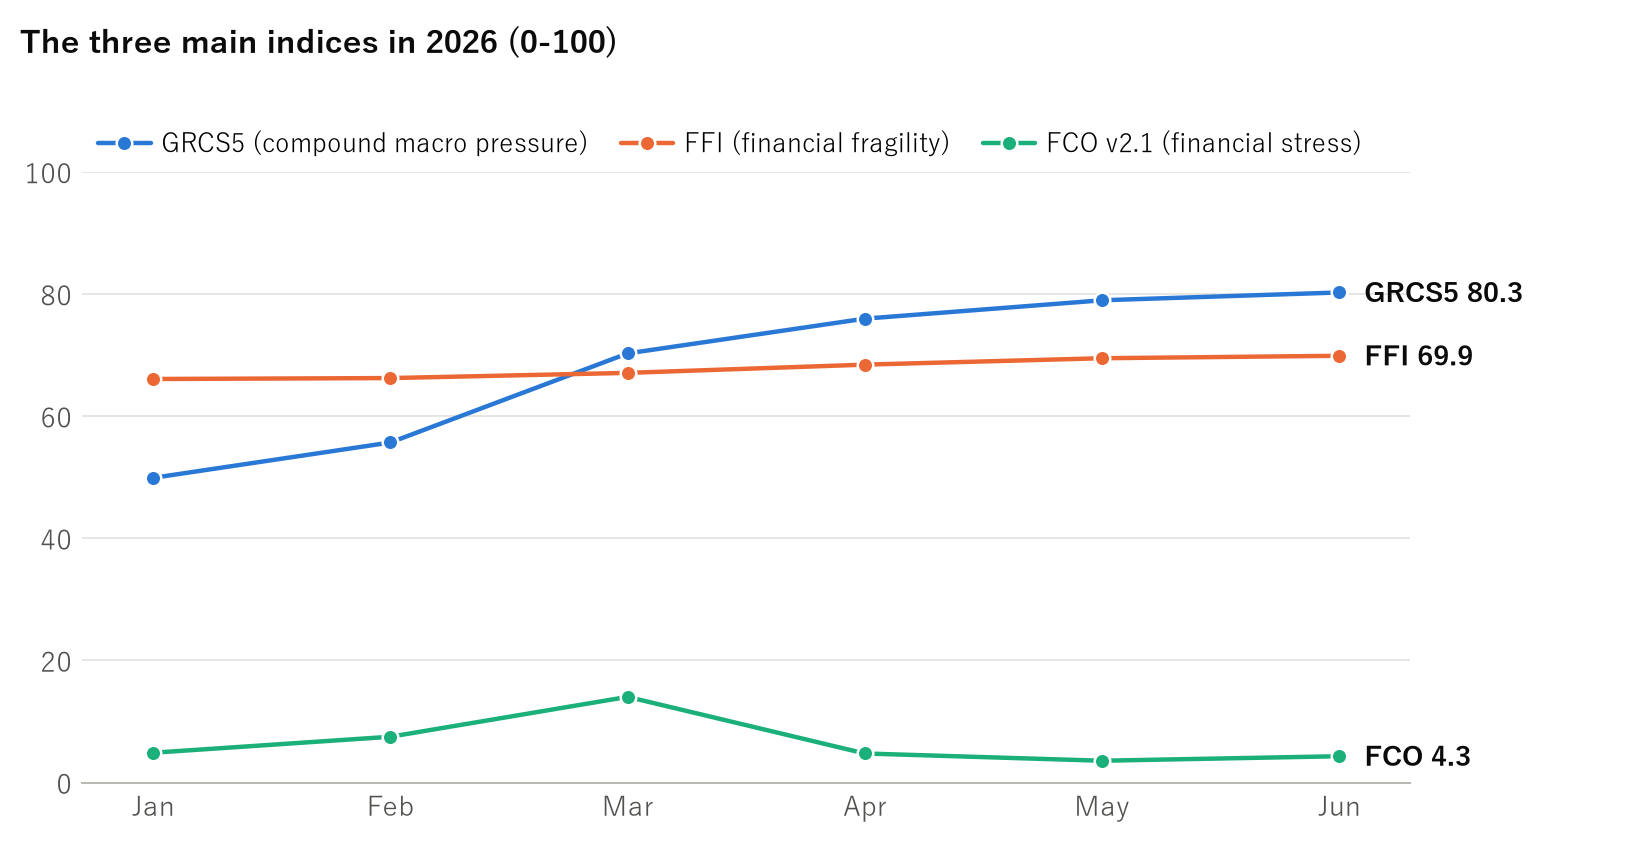
The distance between macro pressure and financial stress was already wide at this point.
Regime reading
The regime for June is Compound Macro Stress / Latent Fragility. This reading has held since April, 3 months in a row.
| Month | GRCS5 | FFI | FCO | Regime |
|---|---|---|---|---|
| Jan | 49.91 | 66.10 | 4.89 | Normal |
| Feb | 55.70 | 66.25 | 7.51 | Elevated Macro Stress |
| Mar | 70.29 | 67.10 | 14.04 | Elevated Macro Stress |
| Apr | 75.98 | 68.45 | 4.77 | Compound Macro Stress / Latent Fragility |
| May | 78.99 | 69.50 | 3.58 | Compound Macro Stress / Latent Fragility |
| Jun | 80.27 | 69.90 | 4.32 | Compound Macro Stress / Latent Fragility |
The five major risks
| Risk | M | L | Level | Change | D |
|---|---|---|---|---|---|
| ① Climate, food, water | 3.7 | 4.1 | 76.4 | +6.0 | +1 |
| ② Sovereign, fiscal | 3.4 | 3.6 | 69.2 | +2.6 | 0 |
| ③ Energy, shipping | 4.2 | 4.7 | 87.0 | +1.2 | 0 |
| ④ Politics, geopolitics | 4.3 | 4.7 | 88.4 | −1.4 | +1 |
| ⑤ AI, labor | 2.9 | 2.5 | 55.6 | +2.6 | +1 |
M is the level this month and L is the degree of linkage (each 1-5). Level = (0.7M + 0.3L) × 20. D is direction (−2 to +2) and is not part of the score.
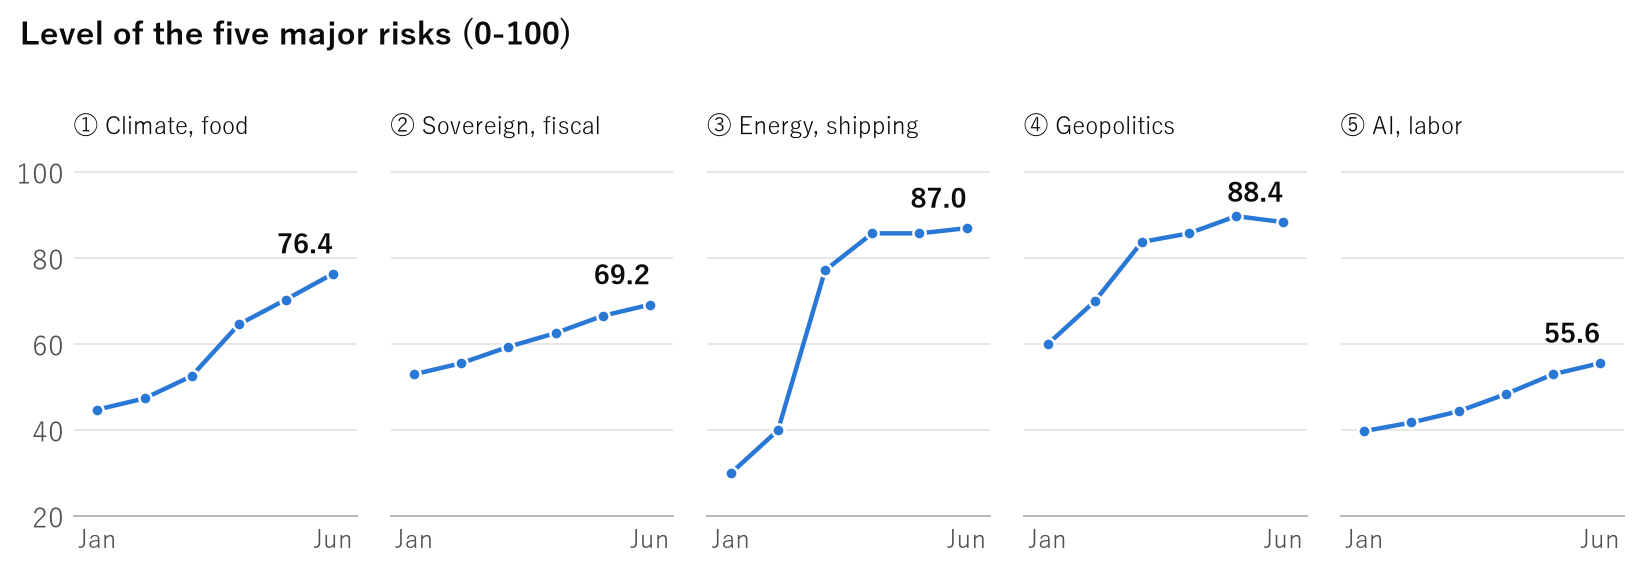
Why the scores moved
- ① Climate, food, water: M rose from 3.4 to 3.7 and L from 3.8 to 4.1. The temperature anomaly moved from 0.55°C to 0.56°C and FAO from 130.8 to 130.4. Prices alone do not explain the rise, and this score carries substantial judgment.
- ② Sovereign, fiscal: M rose from 3.3 to 3.4 and L from 3.4 to 3.6. The 30-year Treasury fell from 5.03% to 4.95%, so the numbers alone do not explain the rise.
- ③ Energy, shipping: M stays at 4.2 and L rose from 4.5 to 4.7. Brent and European gas fell and transits increased.
- ④ Politics, geopolitics: M fell from 4.4 to 4.3 and L stays at 4.7.
- ⑤ AI, labor: M rose from 2.8 to 2.9 and L from 2.3 to 2.5. The share of job cuts attributed to AI fell from 40% to 31%.
Main real-economy indicators
| Indicator | Prior month | This month |
|---|---|---|
| Global temperature anomaly (°C) | 0.55 | 0.56 |
| FAO Food Price Index | 130.8 | 130.4 |
| Brent crude ($) | 107.5 | 85.4 |
| European gas ($/MMBtu) | 16.17 | 15.17 |
| Hormuz transits (per day, press estimates) | 20 | 35 |
| Share of job cuts attributed to AI (%) | 40 | 31 |
Brent and European gas are World Bank monthly averages. FAO values are as published when each report was prepared; later revisions are in the revision record.
Three-layer check of financial contagion
No layer shows contagion. SOFR−IORB is +3bp and the monthly peak in Fed lending is $7.9 billion. Net tightening of bank lending standards was 8.1% in the latest April survey.
| Layer | Indicator | Prior month | This month |
|---|---|---|---|
| Price layer | US HY OAS (%, month-end) | 2.72 | 2.75 |
| Price layer | EM spread proxy (bp) | 314 | 311 |
| Price layer | VIX (month-end) | 15.32 | 16.45 |
| Price layer | STLFSI4 | −0.72 | −0.80 |
| Price layer | 30-year Treasury (%, monthly average) | 5.03 | 4.95 |
| Price layer | 10-year term premium (%) | 0.75 | 0.70 |
| Price layer | Dollar index proxy | 118.88 | 120.92 |
| Credit and leverage layer | NFCI overall | −0.51 | −0.51 |
| Credit and leverage layer | NFCI credit | −0.03 | −0.03 |
| Credit and leverage layer | NFCI leverage | 0.22 | 0.25 |
| Credit and leverage layer | NFCI nonfinancial leverage | −0.56 | −0.54 |
| Credit and leverage layer | Bank lending standards (net tightening %) | 8.1 (April survey) | 8.1 (April survey) |
| Plumbing layer | SOFR−IORB (bp) | −2 | +3 |
| Plumbing layer | Monthly peak in Fed lending ($ billion) | 6.4 | 8.0 |
STLFSI4 and the NFCI series have an average of 0; negative readings are looser than average. The EM spread and the dollar index are proxy series.
Breakdown of FCO v2.1
| Component | Weight | Source value | Score |
|---|---|---|---|
| Credit (HY OAS) | 0.25 | 2.75% | 4.00 |
| Volatility (VIX) | 0.20 | 16.45 | 9.08 |
| Funding (SOFR−IORB) | 0.15 | +3 bp | 5.00 |
| Banks (lending standards) | 0.15 | Expert judgment | 5.00 |
| Liquidity | 0.10 | Expert judgment | 0.00 |
| Intervention use (Fed lending) | 0.15 | 8.0 | 0.00 |
| FCO | 1.00 | — | 4.32 |
FCO is calculated under the current v2.1. It is 5.22 under v2.0. Both are in the Low band.
Breakdown of FFI
| Component | Weight | Prior month | This month |
|---|---|---|---|
| Leverage and credit quality | 0.20 | 72 | 72 |
| Maturity wall | 0.15 | 64 | 65 |
| Valuation and spread compression | 0.20 | 76 | 76 |
| Opaque assets | 0.20 | 72 | 72 |
| Bank lending standards and balance sheets | 0.10 | 57 | 58 |
| External vulnerability (EM) | 0.15 | 68 | 69 |
| FFI | 1.00 | 69.50 | 69.90 |
Social unrest and regional conflict
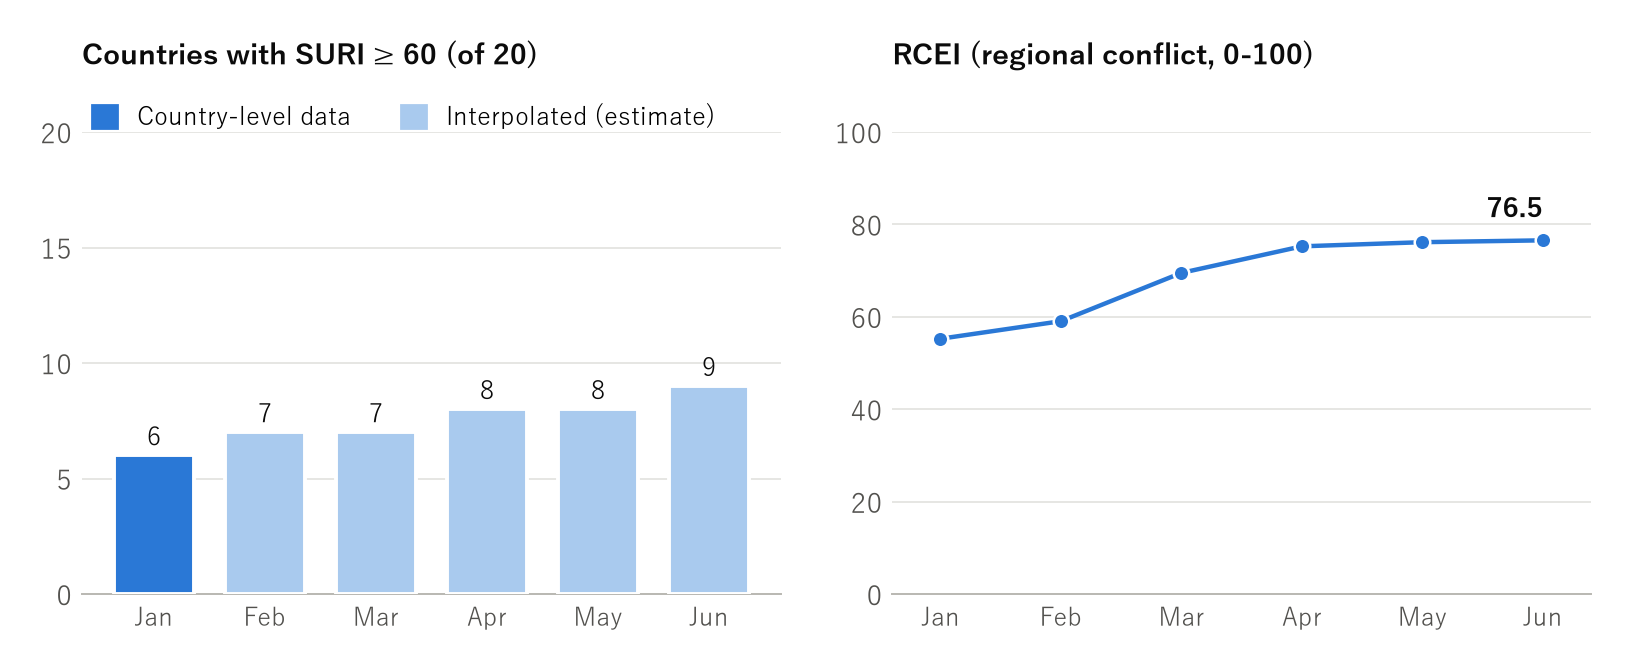
There are no country data for June. We show the actual January and July data side by side and do not build a June country table. Aggregates are interpolated estimates. RCEI moved from 76.15 to 76.55.
| Country | SURI Jan | SURI Jul | Main factors |
|---|---|---|---|
| Sudan | 83.20 | 89.35 | Civil war and famine risk; conflict is the main cause of the food crisis |
| Nigeria | 67.35 | 78.75 | Fuel subsidy cuts, a weak currency and elections; a priority country for monitoring |
| Pakistan | 63.35 | 74.80 | Food, electricity and external debt; a large population |
| Lebanon | 66.60 | 74.00 | Currency and public finances have already broken down |
| Ethiopia | 65.75 | 73.75 | Conflict and drought combined |
| Myanmar | 68.10 | 73.50 | Continuing civil war; armed conflict is the main channel rather than protest |
| Bolivia | 52.70 | 65.20 | Protests against fuel subsidy cuts have spread nationwide |
| Egypt | 55.30 | 65.05 | Bread and fuel subsidies act as a political stabilizer tied directly to public finances |
| Kenya | 49.30 | 61.25 | Fuel price protests with fatalities; protest mobilization stands out |
| Tunisia | 50.55 | 58.70 | Food import dependence and fragile public finances |
| Bangladesh | 48.95 | 58.40 | Food and energy imports; unstable politics |
| Peru | 46.90 | 57.70 | Calmed for now by a fuel subsidy, but public finances have worsened |
| Türkiye | 48.20 | 54.35 | Chronic high inflation |
| Argentina | 49.45 | 54.30 | Austerity and falling real incomes |
| Zambia | 45.15 | 52.75 | Debt restructuring in progress and drought |
| Sri Lanka | 46.35 | 52.50 | Risk of a repeat of the 2022 crisis |
| Ghana | 43.10 | 50.15 | Cost-of-living pressure after debt restructuring |
| Philippines | 39.05 | 44.85 | Rice prices have become a political issue |
| Morocco | 38.25 | 44.55 | Lower farm output due to drought |
| Indonesia | 35.35 | 41.10 | Growing fiscal burden of subsidies |
SURI by country is a set of model estimates based on public information. It is not an official assessment or rating of any country. SURI = 0.35 Household Stress + 0.25 Protest Mobilization + 0.20 Government Fragility + 0.20 Conflict Transmission.
| Month | SURI ≥ 60 | SURI ≥ 75 | Simple average | Population-weighted | GDP-weighted | Maximum | Data |
|---|---|---|---|---|---|---|---|
| Jan | 6 | 1 | 53.15 | 53.38 | 47.80 | 83.20 | Country-level data |
| May | 8 | 2 | 58.55 | 59.04 | 52.74 | 87.30 | Interpolated (estimate) |
| Jun | 9 | 2 | 59.90 | 60.46 | 53.97 | 88.32 | Interpolated (estimate) |
| Component | Prior month | This month |
|---|---|---|
| Combat intensity | 84 | 85 |
| Escalation speed | 76 | 74 |
| State fragility | 63 | 64 |
| Food, energy, water | 71 | 73 |
| Refugees, cross-border | 79 | 80 |
| RCEI | 76.15 | 76.55 |
Strength of the chains
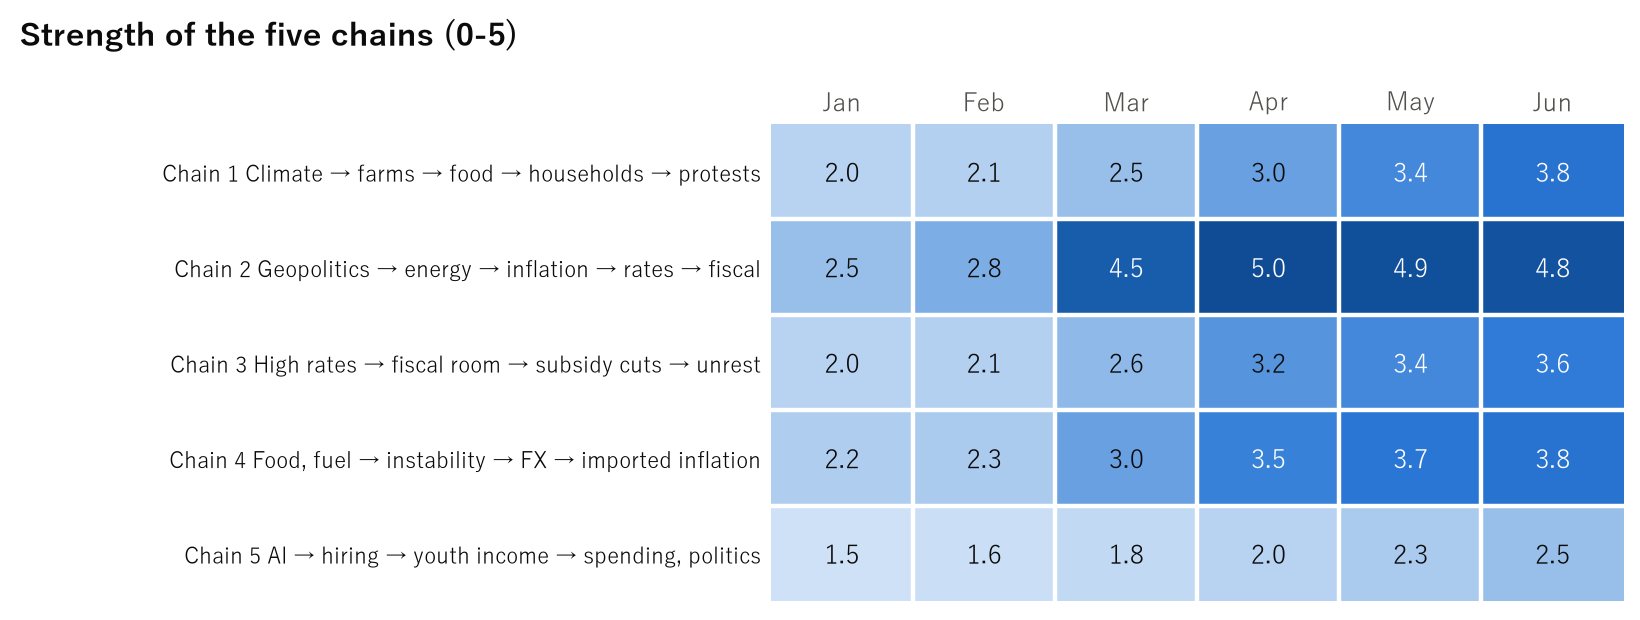
SCI rose from 70.8 to 74.0. Chain 1 rose from 3.4 to 3.8 and Chain 3 from 3.4 to 3.6.
| Chain | Prior month | This month | Change |
|---|---|---|---|
| Chain 1 Climate → farms → food → households → protests | 3.4 | 3.8 | +0.4 |
| Chain 2 Geopolitics → energy → inflation → rates → fiscal | 4.9 | 4.8 | −0.1 |
| Chain 3 High rates → fiscal room → subsidy cuts → unrest | 3.4 | 3.6 | +0.2 |
| Chain 4 Food, fuel → instability → FX → imported inflation | 3.7 | 3.8 | +0.1 |
| Chain 5 AI → hiring → youth income → spending, politics | 2.3 | 2.5 | +0.2 |
| SCI (average of chains × 20) | 70.8 | 74.0 | +3.2 |
Judgmental and objective compared
Judgmental GRCS4 is 83.23 and objective proxy-GRCS is 66.3 (55.6th percentile), a gap of +16.9.
| Month | GRCS4 (judgmental) | proxy-GRCS (objective) | Historical percentile | Gap |
|---|---|---|---|---|
| Jan | 50.77 | 60.7 | 42.5 | −9.9 |
| Feb | 57.07 | 56.8 | 34.1 | +0.2 |
| Mar | 73.15 | 74.1 | 81.6 | −0.9 |
| Apr | 79.14 | 76.0 | 88.0 | +3.2 |
| May | 82.01 | 74.8 | 84.4 | +7.2 |
| Jun | 83.23 | 66.3 | 55.6 | +17.0 |
proxy-GRCS did not yet exist when this report was prepared. The values shown were calculated later with the method unified in October 2026.
Prediction log
The prediction log began with the July 2026 issue, so this issue has no predictions.
What to watch next month
The five watch conditions were set in the July 2026 issue, so this issue has none.
Data revision record
- FCO was recalculated under the current v2.1. It is 5.22 under v2.0.
- Chain, SURI aggregate and RCEI values were prepared for the July issue.
Sources and limits
Limits of this report
- With no commentary at the time, this page contains no interpretation of the news.
- Country SURI aggregates are interpolated.
- Hormuz transits are estimates from press reports. M and L are expert judgment.
- Copernicus C3S (global temperature anomaly)
- FAO (Food Price Index)
- World Bank Pink Sheet (grains, fertilizer, Brent, European gas)
- UNCTAD and press reports (Hormuz transit estimates)
- FRED: 30-year Treasury yield, DGS30
- FRED: 10-year term premium, THREEFYTP10
- FRED: EM spread proxy, BAMLEMHBHYCRPIOAS
- FRED: dollar index proxy, DTWEXBGS
- FRED: US HY OAS, BAMLH0A0HYM2
- FRED: VIX, VIXCLS
- FRED: SOFR (spread to IORB calculated)
- FRED: bank lending standards, DRTSCILM
- FRED: STLFSI4
- FRED: Chicago Fed NFCI and subindexes
- FRED: Fed lending, WLCFLL
- Challenger, Gray & Christmas (job cuts by reason)
- ACLED (protest and battle events, for confirmation)
- IPC (acute food insecurity, for confirmation)
- Caldara & Iacoviello (GPR, Geopolitical Risk Index)
- IMF (PFOODINDEXM, POILBREUSDM)